Commercial banks across East Africa sit on substantial liquid reserves while smallholders starve for long-term capital. The AGF and Mastercard Foundation’s FinRISE initiative seeks to fix the underlying balance-sheet friction.
By Napoleon Mugenzi
KIGALI — Commercial banks across East Africa are not short of capital; they lack the structural incentive to underwrite rural agricultural risk.
Despite accounting for nearly a quarter of Sub-Saharan Africa’s gross domestic product and employing over half its workforce, the agrifood sector absorbs less than 5 per cent of formal bank credit. This imbalance is not an accident of market oversight. It reflects a rational response by commercial lenders to the mechanics of rural enterprise: high transaction overheads, seasonal cashflow volatility, lack of titled real estate for collateral, and acute climate exposure.
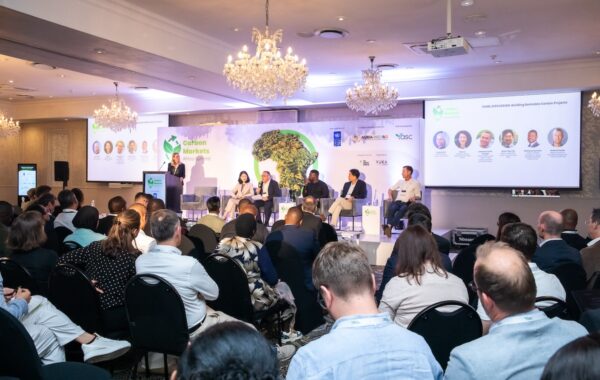
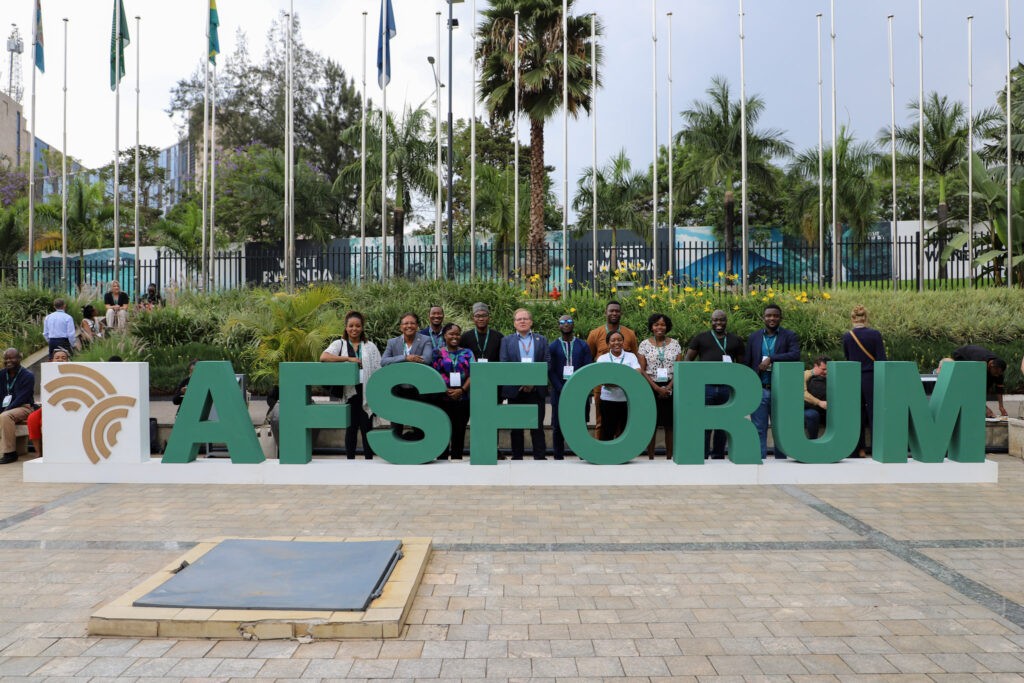
At the AGF Blended Finance Dialogue, held alongside the Africa Food Systems Forum 2026 in Kigali, development finance institutions, microfinance representatives, and commercial bank executives addressed this persistent market failure. Delegates focused on FinRISE—Financial Resilience through Institutional Strengthening and Expansion—a joint initiative by the African Guarantee Fund (AGF) and the Mastercard Foundation designed to recalibrate risk allocation for commercial lenders.
“Africa’s agrifood financing challenge is not simply about having more capital,” delegates noted during the opening sessions of the dialogue. “It is about making finance work better for the businesses that need it most.”
The anatomy of a market structural friction
The financial deficit confronting East African agriculture is rooted in a fundamental mismatch between banking regulations and the economic profile of smallholders. Under conservative central bank frameworks, commercial lenders operating in Kenya, Uganda, Rwanda, and Tanzania are required to hold substantial capital reserves against uncollateralised or high-risk loans.
When evaluating a loan application, credit officers routinely default to land titles as primary security. Yet in rural Africa, where formal land tenure is rare and property rights are frequently customary, small-scale farming enterprises cannot meet standard collateral coverage rules, which often range between 100 per cent and 150 per cent of the principal loan value.
“The conversation underscored that closing Africa’s agrifood financing gap requires more than capital alone,” sector leaders emphasised during the panel discussions. “It calls for better risk-sharing, stronger financial institutions, and solutions that respond to the realities of underserved micro and small enterprises, particularly those operating in rural areas and led by women and young people.”
The consequences of this credit freeze fall disproportionately on women and youth. While women provide the majority of agricultural labor across the region, structural barriers in land ownership severely restrict their ability to pledge real asset collateral. Similarly, young agripreneurs entering processing, distribution, or climate-smart agricultural technology lack the operating histories or asset bases needed to clear traditional bank underwriting criteria.
Concurrently, micro, small, and medium enterprises (MSMEs) in the agrifood value chain face an internal operational bottleneck. Most operate informally, lacking audited balance sheets, corporate governance frameworks, or long-term financial records. For a commercial bank, the administrative cost of conducting due diligence on a $10,000 agricultural loan is virtually identical to that of a $1m corporate line of credit, making small-ticket agricultural lending economically unfeasible under standard operating models.
De-risking the balance sheet through FinRISE
The FinRISE facility attempts to dismantle this double-bind by integrating three complementary financial interventions into a single mechanism: funded risk-sharing guarantees, concessional liquidity, and targeted capacity development.
“Through FinRISE, AGF and Mastercard Foundation are combining funded guarantees, concessional liquidity, and capacity development to address both sides of the financing equation,” delegates explained during technical briefings. “That is strengthening financial service providers, while helping agrifood businesses become more investment ready.”
The mechanics of the mechanism work by directly altering the commercial bank’s risk calculations:
The African Guarantee Fund provides portfolio-level partial credit guarantees, absorbing first-loss positions on qualifying agricultural loans. By taking on up to 50 per cent or 75 per cent of the default risk, the guarantee reduces the regulatory capital reservation required by central banks, effectively freeing up institutional liquidity for rural deployment.
Concessional liquidity supplied through philanthropic and development finance capital lowers the overall cost of funds for tier-two commercial lenders and microfinance institutions. This price reduction allows financial intermediaries to extend loan tenors beyond standard 12-month working capital limits, aligning repayment schedules with crop cycles and longer-term infrastructure investments.
Capacity development funds address institutional knowledge deficits within the financial institutions themselves. Bank credit officers are trained to evaluate agricultural risk using cashflow predictability, satellite data, and harvest cycles rather than relying strictly on landed assets. Simultaneously, technical assistance is deployed directly to rural MSMEs to improve bookkeeping, regulatory compliance, and business planning.
“The ambition is clear,” institutional partners declared as the dialogue concluded. “Move beyond conversations about the financing gap and create the conditions for more sustainable financing to reach more businesses, at greater scale.”
This three-pronged approach directly targets a long-standing criticism of traditional blended finance: that public and philanthropic subsidies often remain concentrated at the top of the pyramid, benefiting multi-million-dollar primary exporters while failing to penetrate local supply chains.
The institutional reality: guarantees are not a panacea
Despite the optimism surrounding FinRISE, industry analysts at the Kigali summit stressed that guarantees alone do not guarantee credit expansion. For commercial banks facing rising non-performing loan (NPL) rates across regional markets, accepting a partial guarantee still leaves them exposed to residual credit loss.
“The goal is for Africa to have more inclusive finance, more sustainable businesses, and more opportunities for its agri-food sector,” representatives affirmed, while acknowledging that institutional inertia remains a significant obstacle.
If a commercial bank’s credit committee views the agricultural sector as inherently unviable due to macro-economic volatility, input inflation, or unpredictable trade policies, a partial risk guarantee simply reduces the magnitude of a loss rather than making the transaction attractive. Furthermore, past experiences with guarantee schemes in East Africa reveal that banks often use guarantees to collateralise existing low-risk clients rather than pushing capital outward into underserved rural frontiers.
The ultimate impact of the FinRISE mechanism will therefore depend on strict covenants and monitoring mechanisms. Development finance institutions must ensure that participating lenders do not capture the concessional subsidy to widen their net interest margins, but instead pass the cost savings down to end-borrowers through lower interest rates and reduced collateral demands.
Until commercial banking in East Africa undergoes a fundamental shift from real-estate-backed lending to cashflow-based risk assessment, the continent’s agrifood financing gap will remain an embedded structural feature of the financial system rather than a temporary shortfall of capital.