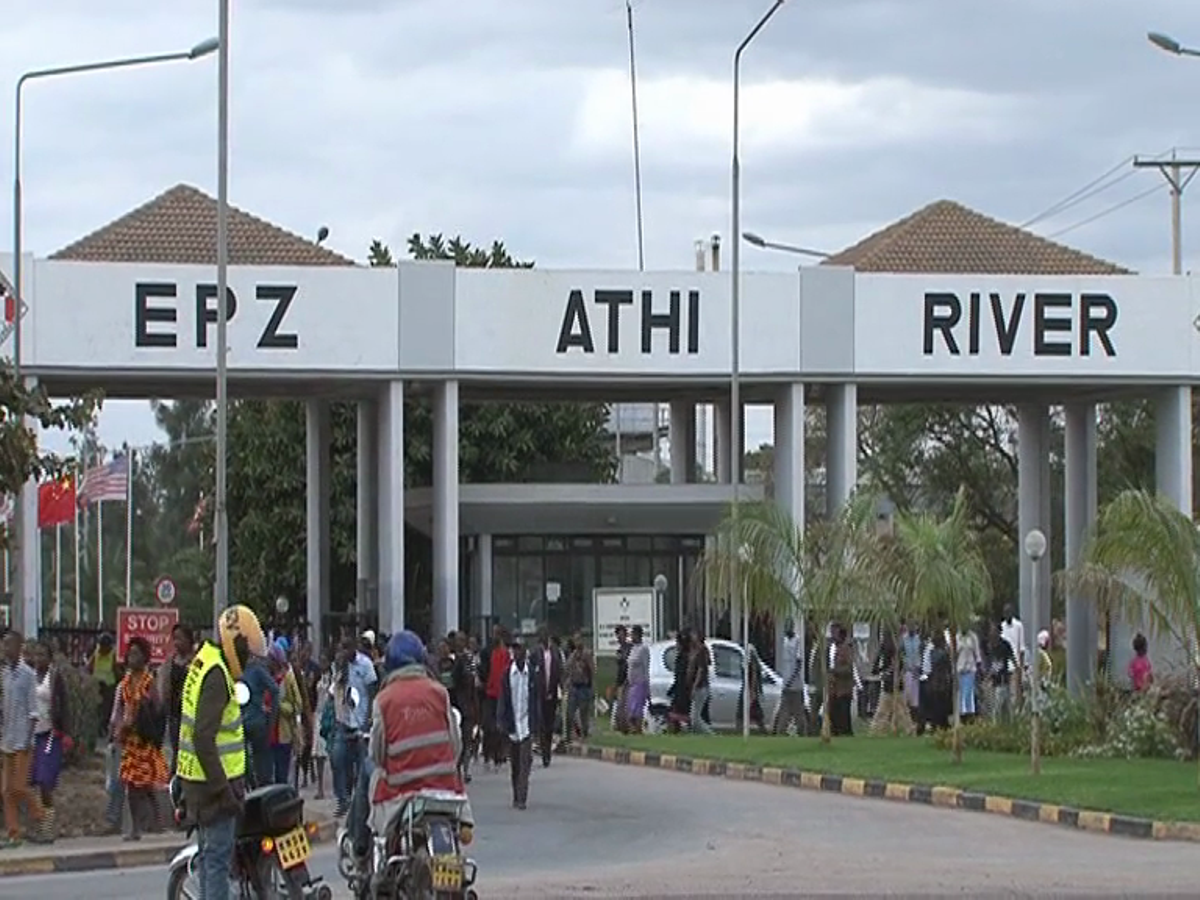
A two-year extension of duty-free access to American markets spares Nairobi an immediate industrial collapse, but short-term political fixes offer little comfort to investors seeking long-term stability.
By Our Reporter
NAIROBI – SIXTY-SIX THOUSAND seamstresses in Athi River Export Processing Zone (EPZ) do not routinely contemplate the arcane machinery of American spending bills. Yet their livelihoods turn on precisely such legislative detritus. With a stroke of his pen, President Donald Trump signed H.R. 6500 into law, incorporating the African Growth and Opportunity Act (AGOA) Extension Act and pushing the trade preference’s sunset to December 31st 2028. For Kenya’s garment magnates, the sigh of relief was palpable. The reprieve, however, is paper-thin.
The bilateral trade numbers are bleak. Last year, overall goods imports to America under AGOA preferences scraped $5.2bn out of $31.2bn in total eligible imports, a tepid fraction of total sub-Saharan commerce, yet vital for specific regional clusters. In Kenya, apparel accounts for roughly 70% of exports bound for American ports, pulling in KSh. 60.6bn ($470m) in 2024. Had the arrangement been permitted to lapse permanently after its nominal expiry in September 2025, or calcified into stop-gap single-year fixes, the resulting tariff wall would have gutted the EPZs ringing Nairobi.
| Trade Preferential Measures | Volume / Scope |
| Total US goods imports from AGOA nations | $31.2bn |
| Goods receiving AGOA preferential treatment | $5.2bn |
| Kenyan apparel exports under AGOA (2024) | $470m (Sh60.6bn) |
| Direct Kenyan jobs dependent on EPZ garment manufacturing | 66,000+ |
Catastrophe is deferred, for now. Lee Kinyanjui, Kenya’s Cabinet Secretary for Investments, Trade and Industry, displayed the obligatory official alacrity in welcoming the signature. “The decision by U.S. President Donald Trump to sign into law the extension of the African Growth and Opportunity Act through December 31, 2028, is highly welcome,” Mr Kinyanjui declared, adding that “the extension of AGOA guarantees Kenyan enterprises continued exports of thousands of product lines to the US without the burden of tariff barriers.”
Crucially, the legislation preserves the third-country fabric provision. The clause allows EPZ factories to stitch trousers from cheap Asian yarn while still claiming duty-free entry into New York; a structural oddity that pure trade theorists wince at, but without which East African assembly plants would simply collapse. Exporters who continued shipping goods while Congress dragged its feet will also see relief; duty paid during the gap will be refundable via US Customs and Border Protection.
Yet the political economy of the fix remains febrile. Manufacturers who endured months of limbo are unlikely to unlock fresh capital on the back of a twenty-eight-month runway. Building an industrial ecosystem requires decade-long visibility; short horizons merely invite sclerosis. Capitalists remain chary, knowing full well that Washington’s protectionist instinct is far from spent, regardless of who occupies the Oval Office.
Then there is the structural conundrum of value retention. By relying heavily on imported raw textiles to turn a profit, the Kenyan apparel assembly line yields meager domestic multipliers; the actual value-add remains strikingly low. Mr Kinyanjui acknowledged the implicit limits of the status quo, noting that “beyond apparel, our focus must now be on using this extended window to expand Kenya’s export basket and increase the range and value of products reaching the US market.” He stressed that “our aim is to use this period to accelerate our manufacturing capabilities, deepen local supply chains and enhance competitiveness,” aiming to make the arrangement “a catalyst for industrialisation, value addition, investment and job creation.”
AGOA was conceived in 2000 as a transitional bridge from aid dependency to commercial self-reliance. A quarter of a century on, the bridge leads mostly back to imported Chinese thread and short-term legislative fixes (politicians, predictably, demurred from pointing out that twenty-six years of preferences have yet to yield a fully integrated domestic supply chain).
To be sure, the retroactive refunding of tariff duties offers immediate liquidity to balance sheets that were looking dangerously bare. Cut-flower growers, coffee farmers, and macadamia exporters will snatch their margins where they find them. But temporary stays of execution do not an industrial strategy make. Exporters have won a breather, nothing more; the clock is already ticking toward 2028.