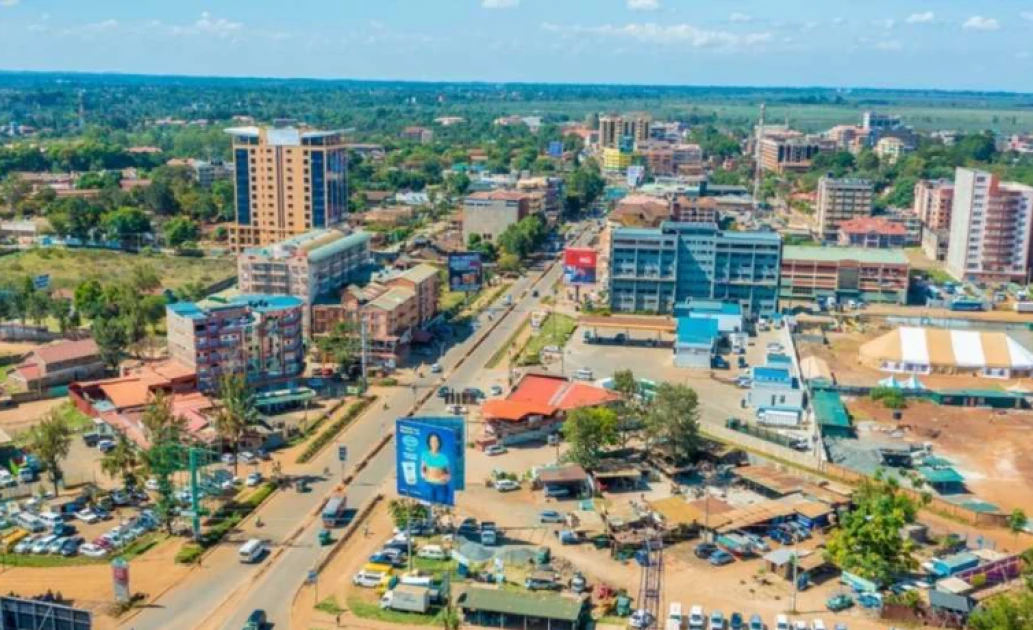
As private capital and state-led programmes race to expand peri-urban housing across Kenya, systemic municipal under-investment is quietly shifting the burden of primary trunk infrastructure directly onto developer balance sheets and household budgets.
By Our Reporter
More than 50 per cent of audited buildings in Kenya fail basic safety standards, even as state-driven housing schemes and private speculative builds race into satellite corridors around major cities.
Data from the Architectural Association of Kenya (AAK) reveals that out of 1,333 structures inspected by the National Building Inspectorate during the 2023/24 financial year, only 43 per cent were certified entirely safe for human occupation. A further 18 per cent (246 buildings) were classified as unsafe, 34 per cent were rated as fair, and 42 structures (3 per cent) were designated as dangerous, requiring immediate testing or outright demolition.
The figures expose a widening divergence between property supply and municipal governance. Across peri-urban belts surrounding Nairobi and other commercial hubs, real estate developers are rapidly putting up housing units to satisfy demand driven by urbanisation and the state’s Affordable Housing Programme. Yet, local utility networks, storm drainage, secondary roads, and waste-management systems have failed to keep pace.
The structural gap is creating an uncounted liability for private developers and households, who are increasingly forced to internalise infrastructure costs through private boreholes, off-grid water treatment, septic systems, and private access roads.
Demographics and the structural deficit
The pressure on peri-urban corridors stems from a persistent supply mismatch in formal urban housing. Industry research and market data indicate an annual urban demand of roughly 200,000 to 250,000 units against a formal supply of approximately 50,000 units per year, accumulating an aggregate national housing deficit exceeding two million units.
Nairobi absorbs roughly three-quarters of this deficit. With the capital projected to reach 14 million residents by 2050, satellite corridors in neighbouring counties have become the primary outlet for residential expansion. Annual growth rates highlight the scale of demographic momentum, with Kajiado expanding at 5.5 per cent annually, Machakos housing over 1.5 million residents, and Kiambu reaching 2.7 million people directly in Nairobi’s growth path.
Property market data from HassConsult shows that land prices in satellite towns like Ruiru, Kikuyu, Syokimau, and Ongata Rongai have consistently outpaced central city land inflation over the past decade, driven by commuter bypasses and rail connections. Institutional developers such as Mi Vida Homes have highlighted a corresponding shift in consumer demand toward integrated suburban communities that promise private utility management over reliant public delivery.
However, where private developers position land acquisitions ahead of state planning, municipal service provision rarely follows at the same pace.
The fiscal friction of unplanned growth
The state’s Affordable Housing Programme reports more than 280,000 units under development across roughly 40 counties, backed by over one million user registrations on the Boma Yangu digital platform. But the sheer volume of construction is colliding with municipal under-investment.
Speaking at the Architectural Association of Kenya 2026 Convention in Diani, Acting Housing Secretary Cassius Kusienya, delivering remarks on behalf of Principal Secretary Charles Hinga, acknowledged the structural lag in state provisioning.
“Our towns are growing faster than the systems that serve them,” Kusienya said, citing failed drainage systems, washed-out roads, saline wells, overheated buildings, and developments situated on flood-prone land as visible symptoms of systemic neglect.
The financial friction created by these infrastructure deficits lands squarely on the private sector. When municipal services fail to arrive, developers must either absorb the extra capital outlay or pass it on to buyers through higher unit prices. In many peri-urban developments, off-grid water supply and private drainage solutions account for a growing share of initial capital expenditure, squeezing developer margins and raising entry costs for prospective homeowners.
+-----------------------------------------------------------------------+
|                       THE PERI-URBAN COST CASCADE                      |
+-----------------------------------------------------------------------+
|                                                                       |
|  1. Municipal Capital Shortfall                                       |
|     Trunk infrastructure (sewage, drainage, roads) lags behind build. |
|                                                                       |
|  2. Developer Infrastructure Transfer                                 |
|     Private capital funds boreholes, septic tanks, & internal access. |
|                                                                       |
|  3. Inflated Unit Capital Outlay                                      |
|     Higher upfront costs passed to buyers; yields compressed.         |
|                                                                       |
|  4. Long-term Asset Depreciation & Retrofit Risk                      |
|     Unsafe structures & poor drainage lead to costly future repairs.  |
+-----------------------------------------------------------------------+
Systemic risks and long-term assets
Building safety failures compound these economic risks. In peri-urban areas where regulatory oversight is thin, rapid land-use conversion frequently skips comprehensive environmental and structural audits. The result is a growing inventory of commercial and residential assets exposed to structural weakness and climate shocks.
Speaking at the same conference, Audily Chatora, president of the Zimbabwe Institute of Quantity Surveyors, argued that treating resilience as an optional addition rather than a core engineering requirement leads directly to economic losses.
“Resilience is a shared responsibility, and the cost of inaction is ultimately measured in lives lost and communities left vulnerable,” Chatora said.
For commercial lenders and institutional investors, the lack of trunk infrastructure and structural oversight complicates underwriting. Properties built on unserviced or hazardous land risk rapid physical depreciation, rising maintenance costs, and lower rental yields.
As satellite towns expand, the commercial viability of Kenya’s housing market will depend less on the number of units breaking ground and more on whether municipal planning can deliver the underlying networks required to support them.