How regional consumer brands and global giants are colliding on the shop floors of East Africa, where distribution grit outweighs deep pockets.
By Kirimi Mbogo
In bustling commercial districts and neighbourhood kiosks across Kenya, a quiet war of attrition is playing out over a few centimetres of metal shelving. On one side stand entrenched global giants, multinationals equipped with vast balance sheets, century-old supply chains, and substantial marketing budgets. On the other are homegrown African fast-moving consumer goods producers, whose competitive edge lies not in financial scale, but in an intimate familiarity with the informal trade networks that power everyday commerce across the continent.
For decades, conventional wisdom held that multinational corporations would inevitably sweep aside domestic players as African markets modernised and formal retail expanded. Yet reality has proven far more stubborn. As household budgets contract under the weight of rising living costs, the battle for the African consumer has entered a sharper, more complex phase, one defined less by brand heritage and more by local execution, pricing architecture, and supply chain agility.
The economics of the kiosk
To understand the contest, one must look past the gleaming glass facades of modern shopping malls in Nairobi, Lagos, or Accra. The beating heart of African retail remains traditional trade: neighbourhood dukas, roadside kiosks, and open-air municipal markets. Industry data from retail intelligence platforms shows that traditional trade accounts for roughly 58 percent of retail turnover in Kenya, and climbs past 70 to 90 percent in wider sub-Saharan markets.
Multinational heavyweights like Unilever, Nestlé, and Coca-Cola built their historical dominance on extensive distribution networks. However, local competitors have increasingly weaponised proximity and agility. Indigenous manufacturers such as Bidco Africa, Brookside Dairy, and Chandaria Industries understand that an African consumer’s purchasing power is frequently tied to daily or weekly cash flows rather than monthly salaries.
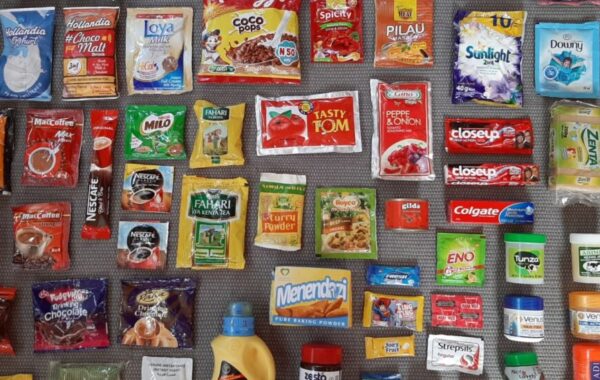
This reality dictates the economics of packaging. Selling a standard multi-dose container of washing powder or cooking oil is often commercially unviable for millions of households facing tight liquidity constraints. Instead, commercial survival requires sophisticated sachet economies, delivering essential goods at price points low enough to fit into a daily wage, yet robust enough to preserve unit margins.
Local producers often adapt to these micro-fluctuations faster than their global peers. Bureaucratic layers sitting in corporate headquarters in London or Rotterdam can slow down product reformulation or packaging pivots by months. By contrast, local manufacturers iterate in real time based on direct feedback from wholesale distributors operating in downtown Nairobi or regional trading centres.
As market analysts note, the traditional retail channel operates on entirely different rules from formal supermarkets. “Neighbourhood shops still decide oil, milk sachets, soap and soda,” notes Sospeter Gichuhi, a retail analyst tracking East African consumer markets. In this environment, agility on unpaved roads matters far more than corporate equity.
Capital, scale, and the multinationals’ counter-offensive
Yet, financial scale remains a formidable weapon. Multinationals possess capital reserves that allow them to absorb prolonged margin compression, weather currency devaluations, and invest heavily in automated manufacturing and aggressive marketing. When foreign exchange shortages or soaring inflation squeeze raw material inputs, such as imported palm oil or industrial wheat, global players can leverage international credit lines and hedging strategies that smaller domestic firms struggle to match.
Furthermore, multinationals are fighting back by localising their supply chains. Rather than shipping finished goods from Europe or Asia, giants like Unilever Kenya have invested heavily in regional manufacturing and local sourcing targets. By sourcing a significant share of raw and packaging materials locally, they aim to bypass foreign exchange bottlenecks and reduce shipping overheads, directly challenging domestic competitors on price.
Data from market research firms underscores this ongoing tension. Kantar’s extensive Brand Footprint analysis reveals that regional and local labels frequently command the lion’s share of consumer choices in emerging markets, capturing formidable loyalty by matching product quality with hyper-local cultural resonance and distribution resilience. Complementing this, research from trade consultancy BDO East Africa notes that “the FMCG sector faces rapid shifts driven by consumer behaviour, technological advancements, and competitive pressures, requiring deep local market expertise to navigate effectively”.
The margin squeeze and the consumer’s choice
The ultimate arbiter in this clash is the consumer, whose loyalty is fiercely transactional. Stubborn inflation and fiscal tightening, exemplified by recent tax adjustments in Kenya that have reined in disposable incomes, have forced households to trade down.
When cooking oil or laundry detergent prices jump, brand loyalty evaporates quickly. Consumers readily switch from premium multinational labels to regional alternatives or unbranded bulk goods. This trend strips away the pricing power that multinationals rely on to justify their higher valuations and overheads.
At the same time, local producers face their own structural hurdles. High energy costs, expensive domestic borrowing rates, and creaking transport infrastructure mean that manufacturing locally is not automatically cheaper than importing. A domestic brand that wins on consumer trust can still bleed cash if its factory-gate costs outpace what inflation-weary households are willing to pay.
The battle for the African consumer is not a zero-sum narrative of local Davids triumphing over foreign Goliaths, nor is it a coronation of multinational dominance. Instead, it is an ongoing negotiation shaped by cost pressures, distribution grit, and the relentless reality of wallet-share economics. The winners will not be those with the loudest marketing campaigns, but those who can most efficiently navigate the messy, cash-based, and fiercely competitive reality of Africa’s retail streets.
What happens next?
As modern retail footprints expand through regional shopping mall developments and digital business-to-business distribution platforms bring visibility to previously opaque informal supply chains, the margins for error are shrinking. Multinationals will continue to deploy their deep pockets to capture the expanding urban middle class, while local players will lean on their unmatched agility and community roots. For both sides, survival depends on a simple rule: price right, distribute deep, and never mistake corporate strategy for market reality.