Why governments favour consumption levies over income tax, and why the poor end up carrying the load
By Kirimi Mbogo
Nairobi’s matatu touts do not read finance bills, but in June 2024 they knew every clause. A 16% levy on bread. Another on cooking oil. A tax on the mobile money transfers that the boda boda economy runs on. Parliament passed the bill on a Tuesday afternoon; by Tuesday night protesters had breached its chambers, and at least twenty were dead. Two days later President William Ruto went on television and, in two words, ended it. “I concede,” he said, and withdrew the bill. The episode was billed as a referendum on debt, or corruption, or eco tax. It was, more precisely, a referendum on consumption tax, and on who actually pays it.
Governments the world over have developed a quiet preference for taxing what people buy rather than what they earn. The reasons are structural, not ideological, and they explain why Kenya’s VAT base has stayed narrow even as its appetite for VAT revenue has grown; why Nigeria doubled down on VAT collection efficiency before touching a notoriously porous corporate tax regime; why Ghana, cornered by a debt restructuring, reached first for an electronic transaction levy rather than a wealth tax it lacked the machinery to enforce.
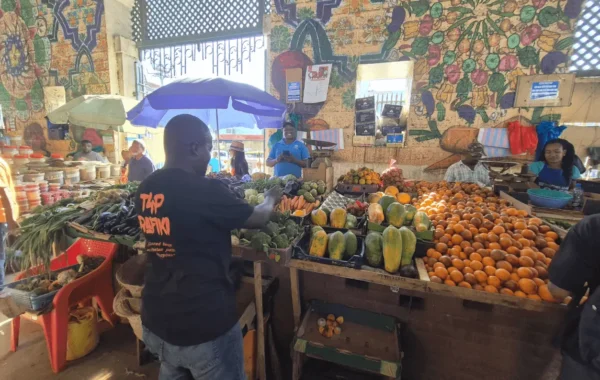
Consumption taxes are, above all, easy to collect. Income tax requires a government to see into households and firms, to audit, to chase. Across much of Africa, where informal employment often exceeds 80% of the workforce, that visibility simply does not exist. Kenya’s own tax authority put the informal sector’s share of the national workforce at 83%, some 15 million people, in a 2023 assessment of how much of the economy it still cannot reach. A boda boda rider selling motorcycle taxi rides for cash leaves no payroll record. A VAT, by contrast, is collected at the point of sale, remitted by the retailer, largely self-enforcing; the shopkeeper who fails to charge it loses margin, not the state. The tax collects itself, more or less, at the till, which is precisely the problem for a revenue authority trying to widen its net any other way.
The numbers on that net are instructive. Kenya’s own tax authority disclosed this year that only 230,000 businesses are registered for VAT against a projected 800,000, leaving a collection gap it puts at roughly Sh378 billion. Its diagnosis, laid out in an internal strategy document, blamed “weak visibility of the informal economy” as much as outright evasion. That is a tax authority admitting, more or less on the record, that it cannot see the thing it is meant to tax. So it taxes the transaction instead. Consumption is visible even when the consumer is not.
There is a second, less flattering reason governments prefer this route. Consumption taxes are politically anaesthetic in a way income taxes are not. A worker who sees 30% vanish from a payslip develops a sharp, personalised grievance against the state. A shopper who pays 16% more for cooking fat experiences the loss diffusely, spread across a thousand small purchases, rarely itemised, rarely traced back to Treasury. Consider Kenya’s excise regime on mobile money. Safaricom’s M-Pesa processes transactions equivalent to more than half of Kenya’s GDP each year, an infrastructure so embedded in daily commerce that a tax on it functions almost like a tax on breathing. The excise duty on mobile money transfers rose from 12% to 15% in 2023, generating billions of shillings at minimal administrative cost and, crucially, with no need to identify who was sending the money or why. Contrast that with capital gains tax, still a comparatively marginal revenue line in Kenya, requiring valuation disputes, contested asset registries, lawyers.
None of this is unique to Africa; Britain’s VAT and America’s sales taxes function on the same logic. But the burden falls unevenly, and nowhere more so than in economies where the poor spend nearly everything they earn and the rich, comparatively, do not. This is the conundrum sitting at the centre of consumption taxation: administratively elegant, distributionally blunt. A household earning enough only to cover food, transport and rent pays VAT on effectively 100% of its income. A household with money to save, invest or send abroad pays VAT on only the fraction it spends, sheltering the rest entirely. Kenya’s statistics office has found that the poorest households devote close to half their spending to food, most of it now VAT-liable after the government narrowed its list of zero-rated goods in recent years; the wealthiest quintile spends a fraction of that share on food. The tax does not know the difference. It gouges both alike, one much harder than the other.
Governments are not blind to the regressivity; they calculate it as more survivable than the alternative. Zero-rating milk or unprocessed maize flour is one partial fix, common across the East African Community, though it invites its own distortions, since large processors and small vendors alike lobby fiercely for the status. Kenya’s long, unresolved fight over whether bread should be zero-rated says something about how contested even these carve-outs become; VAT policy, in practice, is trench warfare fought item by item on a supermarket shelf.
There is also the matter of who administers the pain. Excise duties on alcohol and cigarettes are popular with finance ministries partly because they double as public health levers, partly because their consumers are, politically, easier to tax than salaried professionals with union representation. Uganda’s excise hikes on beer, and South Africa’s escalating “sin taxes,” both trade on this asymmetry. The revenue is real. So is the assumption, not always borne out, that the burden lands on a class with limited capacity to organise against it.
What the Kenyan protests of 2024 demonstrated, and what finance ministries from Accra to Abuja are quietly absorbing, is that the assumption has limits. Alex Vines of Chatham House, watching Ruto’s reversal unfold, called it “a knee-jerk response” to a movement his government had not seen coming. Consumption taxes may be invisible at the point of collection, but they are not invisible in aggregate. Stack enough small levies atop stagnant wages and a currency that lost a third of its value against the dollar between 2022 and 2024, and the diffusion strategy stops working. People do the arithmetic eventually, usually at the worst possible moment, often at the pump or the till, and the anger that income tax would have delivered in monthly instalments arrives instead in a single furious quarter.
The deeper irony is that consumption taxes were meant to be the mature alternative to income tax: broad based, hard to evade, friendly to investment. In fragile fiscal states they have become something closer to a last resort dressed as reform, deployed because the state cannot see enough of the economy to tax it any other way. Until African revenue authorities can trace income as efficiently as they trace a mobile money transfer, they will keep reaching for the tax that collects itself, and keep discovering, periodically and expensively, exactly whose pockets it was collecting itself from.