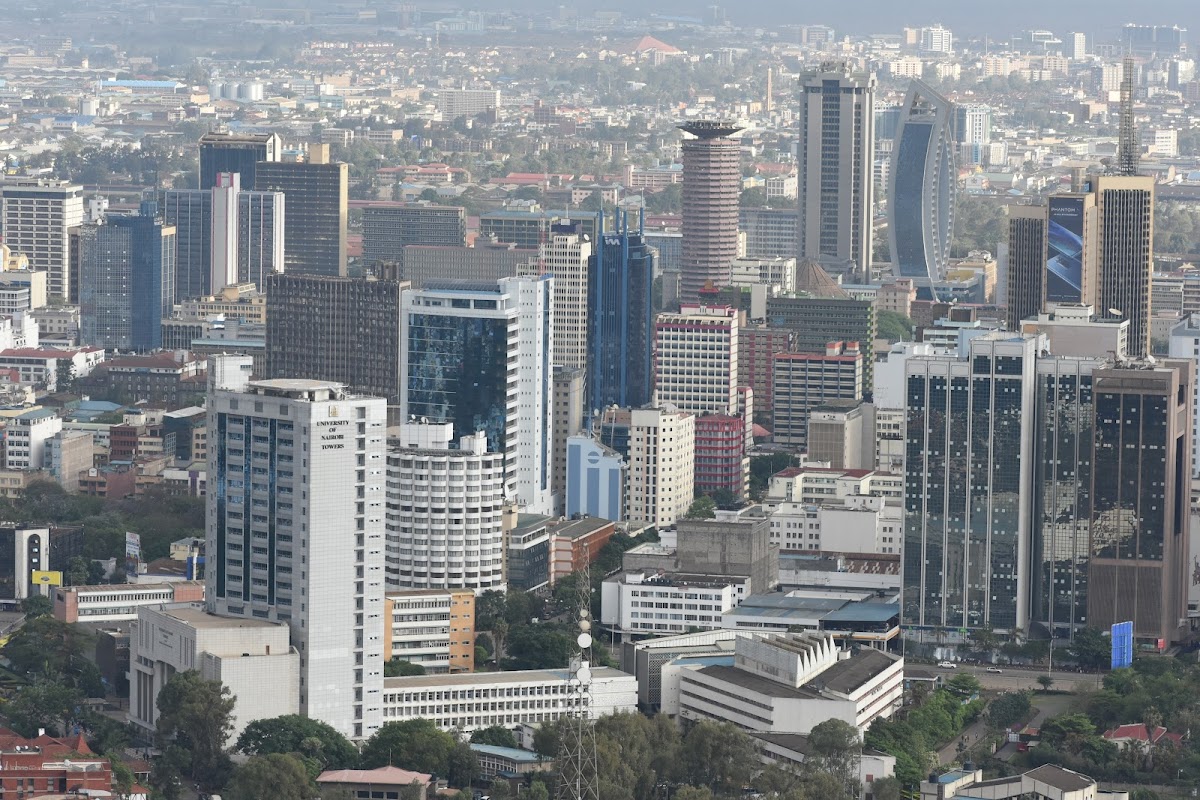
Commercial enterprises across Nairobi and the broader region face a turbulent landscape shaped by sudden tax shifts, county-level regulatory friction, and evolving government mandates, forcing corporate leaders to pair strategic diplomacy with strict fiscal discipline to safeguard their investments
By Our Staff Writer
Navigating Kenya’s commercial landscape requires private enterprises to maintain delicate political relationships while confronting shifting taxation frameworks, regulatory realignments, and mounting fiscal pressures. As East Africa’s primary economic and financial hub, Kenya presents an environment where national legislative agendas and county-level tax policies directly dictate corporate strategy. For business leaders operating across key sectors, surviving market volatility hinges on balancing proactive policy engagement with rigorous internal operational discipline.
Burden of regulatory uncertainty
Unpredictable fiscal adjustments and complex regulatory frameworks remain major operational hurdles for firms operating in Kenya. Annual finance bills and shifting legislative agendas frequently alter the rules of engagement, complicating medium-term corporate planning and raising compliance overheads.
Findings from a World Bank diagnostic report highlight that Kenya’s business environment remains constrained by regulatory uncertainty, high compliance costs, and governance weaknesses that drain billions of shillings in potential investment opportunities. The report notes that while devolution was intended to catalyse local development, it has introduced regulatory friction for firms operating across county borders through fragmented taxes, licences, and administrative fees.
Detailing these systemic headwinds, DW correspondent Andrew Wasik observes that “the overall picture from the World Bank is that Kenya still has many of the ingredients needed to be a major investment destination, but doing business here still remains unnecessarily difficult and expensive,” pointing explicitly to “high and multiple taxes, regulatory uncertainty, a lot of corruption, issues with licensing, and also expensive credit and infrastructure challenges.” He adds that “64% of firms that were surveyed in this report identified tax rates as a major or very severe constraint,” explaining that “the taxes, the multiple taxes and the frequent changes to tax policies are the ones which are actually punishing these businesses.”
For corporate executives, managing this volatile landscape requires continuous strategic discipline and operational endurance. Former Kenya National Chamber of Commerce and Industry Chairman Kiprono Kittony frames this reality by noting that “success is a flipside of the coin in a failing in business, where the only difference is how many times as a businessperson someone is willing to fail, fall, stand up, and try again.”
In response, companies prioritise strict capital preservation and lean cost structures to insulate operations against sudden policy pivots. MyDawa Chief Executive Officer Tony Wood underscores this meticulous operational posture, stating that “as an entrepreneur, one must always be very clever and meticulous in spending to ensure getting the most out of every shilling and dollar used.”
This focus on resilience is echoed across Kenya’s industrial leadership. Former Centum Investment Chairman Chris Kirubi observed that “business is always a struggle, there are always obstacles and competitors, there is never an open road, except the wide road that leads to failure,” adding that “every great success has always been achieved by fight, every winner has scars, and the men who succeed are the efficient few who have the ambition and will-power to develop themselves.”
Navigating such cycles also demands decisive execution during periods of macroeconomic flux. Bidco Africa Chairman Vimal Shah describes this proactive orientation, remarking that “today is the beginning of the rest of your life, you are the pilot of your life, lock in your destination, take off to it, from where you are,” while emphasising that “getting things done is better than having things perfect, done is better than perfect, whatever you have in your hands, get going with it, just do it.”
Navigating state priorities
To mitigate policy risks, major industries increasingly align their operations with state-driven development programmes, particularly in export manufacturing, agriculture, and infrastructure. World Bank estimates indicate that targeted public reforms and private alignment could unlock over 1.5 billion dollars in private investment and create upwards of 88,000 direct jobs over the medium term.
The state continues to push for industrial substitution and local manufacturing to protect foreign reserves and generate employment. President William Ruto outlined this economic transition during a public address, asserting that “the government wants to create ecosystems and avenues to target the export market, moving Kenya away from being a supermarket for other countries to being a producer,” adding that “local manufacturing of clinker and steel has saved the country foreign exchange to the tune of 500 million dollars a year.”
President Ruto also defended the administration’s aggressive tax collection measures as critical for debt management and sovereign self-reliance, stating that “when Kibaki was the President, we used to collect 200 billion shillings in revenue, he helped the country until we collected up to 900 billion shillings, almost 1 trillion shillings,” asking “if he should continue borrowing or go back to Kibaki style to collect more revenues.” He further argued that “these loans will give us more problems, I am in government, I will not be a President who will take the country into the mud, so let us continue collecting tax to build our nation Kenya,” emphasising that “we cannot continue to operate in a space where those in power exempt themselves from paying taxes using all manner of instruments whilst those who do not have as much power pay tax.”
However, analysts and business advocates argue that aggressive tax collection without structural efficiency threatens enterprise growth. Policy and governance expert Inviolata Mwanji notes that debt obligations severely restrict fiscal manoeuvreability, stating that “for every 10 shillings we pay about 6.5 to seven shillings of that revenue earned to paying back debt,” while raising concerns regarding state spending priorities by noting that “we have had a lot of conversations about issues to do with budgeted corruption, and these are some of the things that are financing some of the political initiatives that we are seeing coming from government.”
From the private sector perspective, sustainable growth requires statutory reforms that enhance competitiveness. Kenya Private Sector Alliance Chairperson Jaswinder Bedi highlights structural gaps in labour and trade, noting that “our labour laws over the last 50 years have been static, we need to move from minimum wage to living wage, the two institutions need to work together,” while adding that “we are a large importing economy and we need to move to an exporting economy,” asking “how can we facilitate a balance of trade.”
National Assembly Speaker Moses Wetang’ula affirms the state’s intent to engage commercial leadership on statutory frameworks, stating that “we are open to discussion and sharing ideas to make this country better.”
Institutional agility and networks
Beyond formal lobbying, enterprise stability in Kenya relies heavily on relationship-building, executive leadership, and active participation in industry associations. Maintaining open channels with policymakers enables firms to anticipate regulatory shifts and adapt operational models before legislative changes take effect.
AMREF Senior Corporate Communications Manager Lizz Ntonjira-Mutuma emphasises the commercial value of strategic engagement, noting that “professionals are the sum of the people they spend time with,” advising executives to “attend networking events, request meetings, and get to know the movers and shakers in their industry and related fields, because since business is so relationship-based, these networking efforts can open doors.”
Econet Group Executive Chairman Strive Masiyiwa reinforces the necessity of trust-based partnerships in regional markets, observing that “leaders should not be transactional in their relationships with people but be genuine, because trust will grow from there and that is a currency you cannot buy but is worth so much more.” He also notes that “a vision on its own is not enough, hard work and dedication is required to make that vision a reality.”
Reflecting on the decisiveness required to execute in complex markets, Cellulant Co-founder Ken Njoroge adds that “if I had worried about everything that could go wrong, I would never have started, sometimes you just need to take a leap of faith.” As Kenya’s political and economic climate continues to evolve, private sector resilience will depend on a combination of institutional positioning, strict financial management, and persistent public policy engagement.